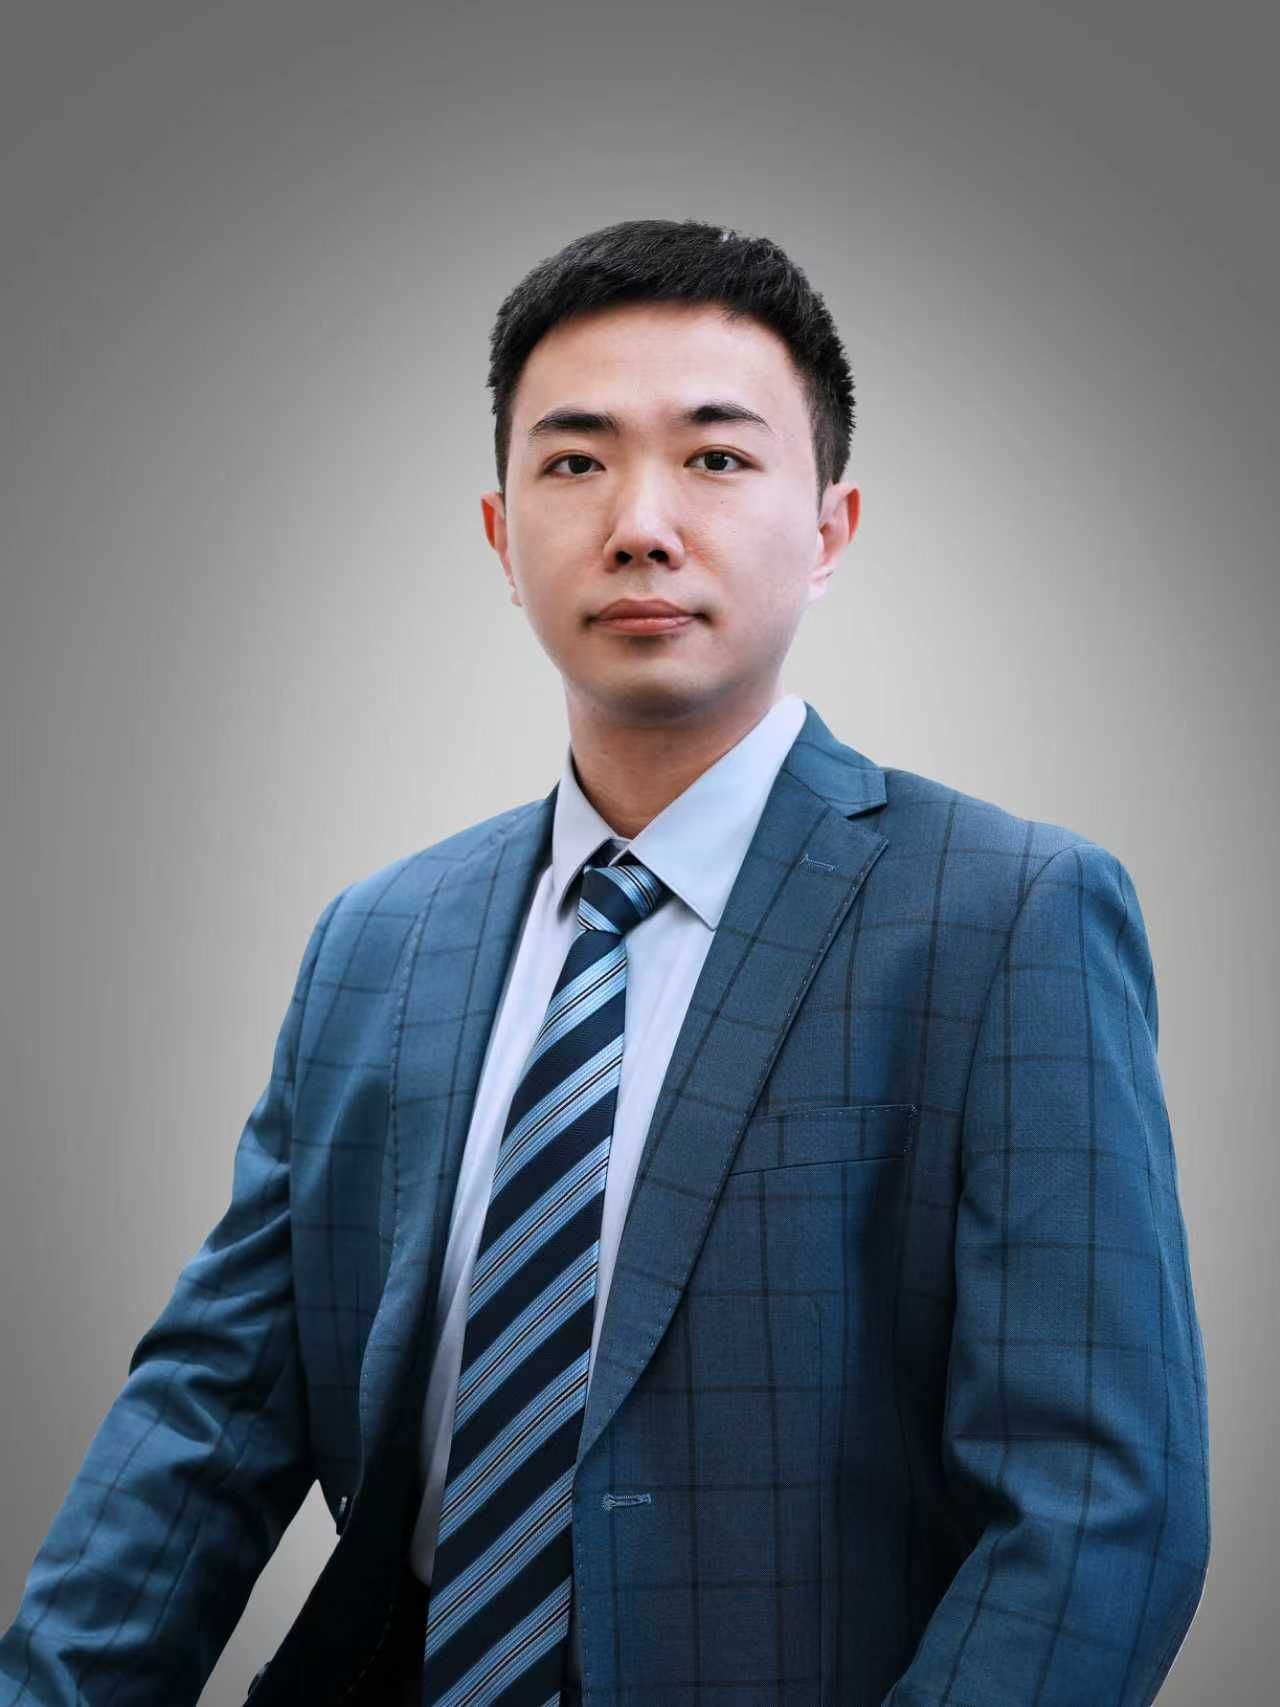
Yifei Chen 陈逸飞
Assistant Professor of Accounting
School of Accounting
Southwestern University of Finance and Economics
01
About
I am an accounting scholar at the School of Accounting, Southwestern University of Finance and Economics (SWUFE). I earned my Ph.D. in Management from Rutgers Business School in 2020.
My work examines corporate disclosure, corporate social responsibility, human capital, textual analysis, capital markets, and financial market investment. My research has been published in the Journal of Accounting and Public Policy, Journal of Business Finance & Accounting, Journal of Business Ethics, Journal of Business Research, Regulation & Governance, and Investment Analysts Journal.
02
Publications
* Corresponding author.
-
2026
Social safety nets and corporate tax avoidance: Evidence from paid family leave programs
Abstract. Social safety nets are essential to a resilient and adaptive economic system. This study examines their influence on corporate tax avoidance using the staggered implementation of U.S. state-level paid family leave (PFL) programs, social safety net policies designed to enhance employees' work-life balance, as a quasi-natural experiment. We find a statistically and economically significant decline in corporate tax avoidance following PFL adoption. The results hold across various robustness tests. A structural equation model shows that the effect is mediated by decreases in employee turnover and improvements in employee productivity. The effect is stronger among firms facing greater financing frictions and among labor-intensive firms. Overall, this study identifies a reduction in corporate tax avoidance as an unintended consequence of social safety nets.
-
2026
Work-life balance and earnings management: Evidence from paid family leave policies
Abstract. This study examines the causal relationship between employees' work-life balance and firms' earnings management behavior. We conduct a quasi-natural experiment by exploiting the U.S. state-level staggered implementation of Paid Family Leave (PFL) policies, which improve work-life balance for employees. We hypothesize that PFL policies improve firms' implicit terms of trade with employees, reducing the need to attract human capital by signaling profitability through upward earnings management. Using a stacked difference-in-differences model comparing firms in states that implemented PFL policies to firms in adjacent states without such policies, we document a statistically and economically significant decrease in upward earnings management for firms in PFL states following PFL implementation. Channel analysis demonstrates that improvements in work-life balance, declines in job vacancy duration, and reductions in employee turnover mediate the negative association between PFL implementation and upward earnings management. The association is stronger for firms with greater labor intensity, more female employees, and when the PFL policies offer higher benefits.
-
2026
Product-harm crises and corporate tax reporting
Abstract. Product-harm crises represent pervasive corporate challenges and influence a wide range of managerial decisions. This study examines the effect of such crises on firms’ tax reporting practices. We find that firm-years with product recalls exhibit significant decreases in tax reserves and effective tax rate compared to control firm-years. These decreases are stronger for recalls occurring closer to year-end, suggesting that firms leverage tax reporting as a last-chance earnings management tool in response to recalls. The effect of recalls in reducing tax reserves is stronger when pre-managed earnings are below analysts’ targets and when managers’ equity risk incentives are high, but weakens when firms face greater reputational concerns or public scrutiny. It also intensifies when recalls are more severe or mandated by regulators, when firms have tax-related internal control weaknesses, and when firms’ auditors are busier. These findings reveal product market disruptions as important economic events driving firms’ tax reporting practices.
-
2026
Workers’ voices matter: Crowdsourced employee reviews and insider trading
Abstract. This study investigates the influence of crowdsourced employee reviews on insider trading behavior. Leveraging the staggered timing of first-time employee reviews about their employers on Glassdoor.com, we employ a stacked difference-in-differences (DID) model comparing firms with review initiations to those without reviews during the same period. Our findings reveal a statistically and economically significant decrease in insider trading activities for firms with review initiations. The results hold across a series of robustness tests, including propensity score matching, entropy balancing, and alternative time windows for the DID setting. Further analyses suggest that insiders scale back their informed trading activities and earn lower abnormal trading profits following review initiations. The effect is stronger for firms with higher litigation risk, greater reputational cost, stronger labor market pressure, recent employee exploitation incidents, and when the reviews are more negative. Overall, these findings suggest that crowdsourced employee reviews discipline unethical insider trading behavior.
-
2026
Corporate social responsibility and employee information sharing
Abstract. This study investigates the association between corporate social responsibility (CSR) and the informativeness of employee-shared information. Focusing on employee reviews for U.S. publicly-listed firms from Glassdoor.com, we find a significantly positive association between firms’ CSR performance and the magnitude of market reactions to these reviews. The results hold across various robustness tests. Channel analyses demonstrate that this positive association is due to reviews for firms with stronger CSR performance providing a greater volume of information and being perceived as more credible. Moreover, employee ratings for firms with stronger CSR performance exert greater influence on stock prices, are less likely to be overly optimistic, decline more sharply following irresponsible social practices, and better predict future operating performance. Review sentiment for these firms also exerts a stronger impact on stock prices. Textual analyses of employee reviews further indicate that a socially responsible culture is considered important in firms with strong CSR performance and is positively associated with the magnitude of market reactions to those reviews. The main results hold using an alternative sample of employee reviews for Chinese publicly-listed firms. Collectively, these findings suggest that strong CSR performance reflects a socially responsible culture that fosters more informative disclosures by employees.
-
2026
Performance-induced CEO turnover in China
Abstract. Analyzing performance-induced CEO turnover offers insights into the turnover-performance relationship and the effectiveness of corporate governance. Correctly identifying forced CEO turnover is fundamental. Breaking from the predominant subjective approach, this study classifies performance-induced turnover using objective data, focusing on an emerging market. Using Chinese A-share listed firm data, we estimate the probability of performance-induced CEO turnover. Then, we find that the likelihood of performance-induced CEO turnover declines significantly as a firm’s return on assets (ROA) increases. Specifically, when firm performance falls below the fourth ROA decile, most CEO turnovers — both forced and voluntary — are performance-induced. We report that industry conditions have a greater effect than stock market cycles on the forced proportion of performance-induced CEO turnovers. Uncertainty shocks reduce performance-induced turnover, while policy shocks decrease it by weakening market competition. Furthermore, delisting risk increases the likelihood of performance-induced turnover while state-owned enterprises have a lower probability of performance-induced turnover.
-
2025
Financial analysts’ information role on brand capital
Abstract. Self-created intangible assets are crucial in firm valuations but are difficult for investors to evaluate because they are not recognised in financial statements. This study examines whether sell-side financial analysts contribute to the market’s understanding of the value of brand capital, an important type of self-created intangible assets. Measuring brand capital as a portion of the difference between a firm’s fair value and its book value, we find that market reactions to analysts’ forecasts and recommendations are stronger for brand-intensive firms, especially when analysts discuss brands in their reports, when analysts are experts in analysing brand capital, and when the firms’ brand capital valuations are more complex. Overall, we find consistent evidence that analysts help investors resolve brand-oriented information asymmetry.
-
2024
Corporate social responsibility and information asymmetry: Do earnings conference calls play a role?
Abstract. This study examines whether firms’ corporate social responsibility (CSR) performance affects the informativeness of their earnings conference calls. Controlling for confounding information from earnings releases, we find a positive association between CSR performance and the magnitude of market reactions to conference calls. This association persists after controlling for systematic differences between firms with strong and weak CSR performance. A structural equation model further demonstrates that this positive association is due to firms with strong CSR performance providing a greater amount of information, whereas no evidence suggests that the positive association is attributable to the market perceiving the information to be more credible. We also find incremental effects of managers’ tone and firms’ possession of future unfavorable information on the positive association between CSR performance and the market reactions to the calls. Moreover, CSR performance is associated with reductions in financial analysts’ forecast dispersion. Overall, these results are consistent with the idea that the ethical standards associated with CSR performance promote informative disclosures.
03
Working Papers
-
Social safety nets and motivation crowding of corporate social responsibility: Evidence from a quasi-natural experiment.
Research Summary. We examine how social safety nets affect firms’ employee-focused corporate social responsibility (CSR) engagement, using a difference-in-differences design exploiting the staggered implementation of Paid Family Leave (PFL) programs in the United States. We posit that PFL programs may either (1) reduce such engagement by weakening the human resource management (HRM) value of CSR initiatives that affect employee-related outcomes similarly to these programs, or (2) increase such engagement by strengthening the HRM value of initiatives that complement these programs. We find an average reduction in employee-focused CSR following PFL implementation, specifically in family leave benefits and DEI-related policies, alongside some evidence of increased daycare benefits that complement PFL programs. Improvements in employee-related outcomes help explain the reduction in employee-focused CSR and remain evident despite this reduction.
Managerial Summary. We study how U.S. state-level PFL programs — a form of family-supportive social safety net — affect firms’ CSR engagement toward employees. These programs may prompt firms to scale back CSR initiatives that provide similar human resource management (HRM) benefits, while encouraging CSR initiatives that complement them. We find that, on average, firms reduce employee-oriented CSR after PFL adoption, but also expand some complementary CSR initiatives. The reduction occurs because PFL programs lessen firms’ reliance on employee-oriented CSR to improve employee-related outcomes, and does not offset these improvements following PFL adoption. The results imply that firms may reduce some employee-oriented CSR without harming employee-related outcomes as social safety nets strengthen family leave benefits, and should rebalance CSR investments in response to changes in family-supportive institutional contexts.
-
Spillover effects of tax litigation via director interlocks and the mitigating role of corporate social responsibility.
Abstract. Tax litigation often arises from aggressive tax avoidance that imposes external costs on society. This study examines the spillover effect of tax litigation among firms with common directors, and the role of corporate social responsibility (CSR) in shaping this effect. We find statistically and economically significant negative market reactions to firms (focal firms hereafter) around the filing dates of tax litigation against director-interlocked peers (litigated peers hereafter). The negative reactions are more pronounced when the tax litigation is more severe, when interlocking directors hold leadership, finance, or governance roles, and when the litigated peers receive greater media attention. We also document a positive association between the CSR performance of focal firms and their market reactions. This association attenuates as CSR performance becomes stronger, is driven primarily by CSR activities that benefit secondary stakeholders or society at large, and is stronger when focal firms are more tax-aggressive. Overall, the findings are consistent with a negative spillover effect of tax litigation through director interlocks and with CSR performance mitigating this spillover effect.
-
Reputational penalty spillover of financial fraud and ESG performance: Evidence from director-interlocked firms.
Abstract. The spillover effects of reputational penalties resulting from peer firms’ unethical behavior is a widespread phenomenon, yet little is known about how firms respond to such effects. This study addresses this gap by examining whether firms engage in ESG activities in response to reputational penalty spillovers from financial fraud committed by peer firms that share common directors. Using a stacked difference-in-differences model, we find a significant increase in ESG performance following peers’ fraud. The effect is concentrated in the year immediately following the fraud, consistent with the ESG response being a short-term risk management strategy. The results are robust to propensity-score-matching, excluding alternative spillover channels, and using alternative fraud measures. The increase includes improvements in the environmental and social dimensions, which offer insurance-like protection against negative stakeholder judgments. The effect is stronger when interlocking directors hold leadership roles or serve on audit or governance committees, when affected firms face higher media coverage, and when the fraud is more severe. Overall, the findings suggest that firms resort to ESG activities to mitigate spillovers of reputational damage.
-
Signals in the shadows: How dark web information shapes financial markets.
Abstract. We examine whether firm-specific information posted on the dark web reaches stock prices, and who trades on it. Using 297,935 dark web posts collected by a commercial monitoring service between February and July 2020, we identify 3,068 firm-days on which a post names a U.S. public firm and measure each post’s sentiment and financial content with pre-trained language models. The content of dark web posts appears in surface web news about one week later, and this lead survives restricting news to first-time stories. Returns around posts vary with post sentiment: negative posts are followed by cumulative abnormal returns of about -1% within a week, and the relation is stronger for posts with financial content. Insiders’ trades after a post are markedly less profitable than their trades before it. Institutional holdings and short selling move in the direction of dark web sentiment; retail order flow does not. The evidence indicates that the dark web moves information about firms into prices ahead of conventional channels, and that the associated trading profits shift from corporate insiders to sophisticated investors rather than to the public.
-
Corporate social responsibility and whistleblowing.
Abstract. We document a positive association between social performance and whistleblowing through three different channels. Employees in firms with stronger social performance are more likely to whistleblow on wrongdoing, consistent with their speak-up culture. The relation is weaker in states with greater increases in unemployment benefits, consistent with social performance lowering retaliation risk. Since firms with better social performance have fewer disgruntled employees, their cases are associated with more negative announcement returns. They are also more likely to have merit based on regulatory decisions, more effective in deterring future financial misconduct, and result in better long-term stock market performance.
04
Teaching
- 01
Fundamental Accounting I
Southwestern University of Finance and Economics
- 02
Accounting Theory
Southwestern University of Finance and Economics
- 03
Introduction to Financial Accounting
Rutgers Business School
- 04
Intermediate Accounting II
Rutgers Business School
05
Education
- 2020
Ph.D. in Management
Rutgers Business School, Rutgers, The State University of New Jersey · Advisor: Dan Palmon
- 2015
B.Econ. in Finance
School of Finance, Southwestern University of Finance and Economics
06
Academic Service
Ad hoc reviewer for the following journals:
- 01
Journal of Business Ethics
- 02
Journal of Business Research
- 03
Journal of Accounting, Auditing & Finance
- 04
Review of Quantitative Finance and Accounting
- 05
Global Finance Journal
- 06
Journal of Emerging Technologies in Accounting
- 07
Investment Analysts Journal